
Appraisal Requirements for Refinancing a Home: What to Expect
Appraisal requirements for refinancing a home explained: why lenders order them, what appraisers check, and when a waiver may save you time and money.
By Daniel Adler
Refinancing a home can feel like a straightforward math problem: you swap an old loan for a new one with better terms, and your monthly payment drops. But before any of that happens, your lender wants proof that the house backing the loan is actually worth what everyone claims. That proof usually comes in the form of a home appraisal. Understanding the appraisal requirements for refinancing a home helps you avoid surprises, plan for the cost, and move through the process with fewer delays. Whether you are chasing a lower interest rate, cashing out equity, or dropping mortgage insurance, the appraisal step sits near the center of the refinance timeline. This guide breaks down why appraisals are ordered, what appraisers look at, when you might skip one, and how lender rules can change the whole picture.
Why Lenders Order an Appraisal for a Refinance
A refinance is not just a paperwork shuffle between you and your current lender. In most cases, the old loan is paid off and replaced with a new one, and that new loan is secured by the same house. The lender needs an independent opinion of value because the property is the collateral. If the home is worth less than the loan amount, the lender carries more risk. An appraisal gives the lender a defensible number to work with, one that is not based on your estimate, a neighbor's guess, or an online valuation tool.
There is also a regulatory layer. Many refinances are later sold to investors or backed by government entities, and those parties require a professional valuation. Even when a lender keeps the loan in its own portfolio, internal risk rules often mandate an appraisal. The appraisal protects the lender, but it also protects you in a roundabout way: it confirms that you are borrowing against real value rather than an inflated figure that could leave you underwater later.
For a rate-and-term refinance, the appraisal mainly confirms that the property still supports the loan balance. For a cash-out refinance, the appraisal becomes even more important because the amount you can borrow is tied directly to your home equity. A higher appraised value can mean access to more cash; a lower one can shrink your plans. Either way, the report is a central input in the lender's decision.
What an Appraiser Evaluates During a Refinance Appraisal
A refinance appraisal is not a home inspection. The appraiser is not looking for every loose shingle or testing the furnace for safety. The job is to estimate market value as of a specific date, using a combination of property details, market data, and professional judgment. Most appraisers follow a uniform approach that considers the property's features, its condition, and how it compares to similar homes that have recently sold.
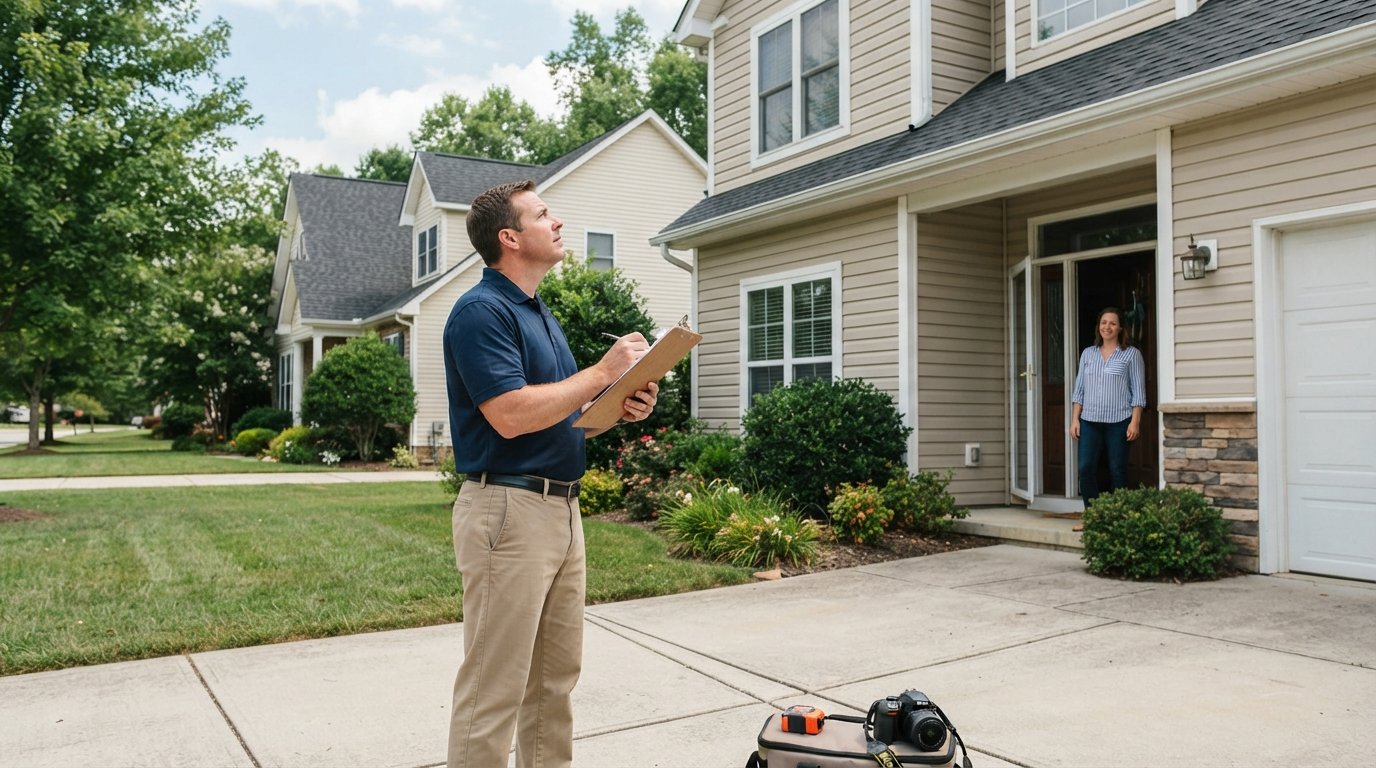
The appraiser typically walks through the home, measures the square footage, notes the number of bedrooms and bathrooms, and records the general condition. They may take photos of the exterior and interior, note any recent updates, and check for features that affect value, such as a garage, a finished basement, or a large lot. Outside the house, they look at the neighborhood, nearby amenities, and any issues that could affect marketability, like a busy road or an adjacent commercial property.
The report itself usually includes several key components. Here is what lenders and borrowers commonly see:
- A property description covering size, layout, age, and condition.
- Comparable sales (comps) of similar homes that sold recently in the area.
- Adjustments made for differences between the subject property and the comps.
- An opinion of market value and the effective date of that opinion.
- Notes on any physical issues observed, plus photos and a location map.
Appraisers do not simply average nearby sale prices. They adjust for differences. If your home has an extra bathroom but the comparable sale down the street does not, the appraiser may add value to your property in the analysis. If your home lacks a garage that most comps have, they may subtract value. The final number is a professional opinion, not a guarantee, and it can differ from what you see on consumer real estate websites.
Condition and Safety Observations
While an appraisal is not an inspection, appraisers do note conditions that could affect value or marketability. Peeling paint, a leaking roof, or a broken window may not kill the deal, but they can appear in the report. Some loan programs have minimum property standards, and serious issues can require repairs before the loan closes. It helps to address obvious problems before the appraiser visits, not because you are hiding anything, but because a well-maintained home tends to produce a smoother report.
When an Appraisal Waiver May Be Possible
Not every refinance requires a full appraisal. In recent years, automated valuation models and appraisal waiver programs have become more common. A waiver means the lender accepts an algorithmic value estimate instead of sending an appraiser to the property. This can save time and money, and it can simplify the process for borrowers with straightforward files.
Waivers are not guaranteed, and they are not something a borrower can simply request and receive. The lender runs the loan through an automated system, and that system decides whether a waiver is eligible. The logic behind the decision is not fully public, but certain patterns tend to matter. A strong credit profile, a low loan-to-value ratio, a stable property history, and a loan amount that fits within certain limits can all improve the odds. Cash-out refinances are less likely to receive waivers than rate-and-term refinances, and properties with unusual features or limited comparable sales may also be less eligible.
Even when a waiver is available, it is not always the best outcome for the borrower. An appraisal can confirm that your home is worth more than the automated estimate, which could reduce your loan-to-value ratio and improve your pricing. If you are counting on a specific value to drop mortgage insurance or access equity, a full appraisal may work in your favor. The waiver is a convenience, not a universal upgrade.
How Lender Requirements Vary
Appraisal requirements for refinancing a home are not set by a single national rulebook. Different lenders, loan programs, and investor guidelines create a patchwork of expectations. A conventional loan backed by Fannie Mae or Freddie Mac may follow one set of rules, while an FHA refinance, a VA refinance, or a jumbo loan may follow another. Some lenders order a full appraisal on nearly every refinance; others lean heavily on automated systems and waivers.
Property type also matters. A single-family home in a subdivision with plenty of recent sales is easier to value than a unique property, a rural home with acreage, or a condominium with non-warrantable features. In those cases, lenders are more likely to require an appraisal even if a waiver might otherwise be considered. Loan size can play a role too, since jumbo loans often carry stricter valuation requirements.
Because requirements vary, the best approach is to ask specific questions early. Before you apply, ask the lender whether an appraisal is likely, who orders it, who pays for it, and what happens if the value comes in lower than expected. If you are comparing offers, compare the appraisal policies alongside the rates and fees. A loan with a slightly higher rate but a predictable appraisal process may be easier to plan around than one with unclear valuation rules.
What the Appraisal Process Looks Like Step by Step
Once you apply for a refinance, the appraisal usually happens after the initial paperwork and disclosure stage. The lender orders the appraisal through an appraisal management company or a direct vendor, and a licensed appraiser contacts you to schedule a visit. The visit itself often takes 30 to 60 minutes, depending on the size of the home. After the walkthrough, the appraiser completes research, writes the report, and delivers it to the lender.
Here is a typical sequence for borrowers:
- Apply for the refinance and provide basic financial and property information.
- The lender orders the appraisal and discloses the cost to you.
- The appraiser schedules and completes the property visit.
- The appraiser researches comparable sales and submits the report.
- The lender reviews the report and confirms whether the value supports the loan.
Timing can vary widely. In busy markets, appraisers may be booked out for a week or more, and report turnaround can add another several days. Some lenders use digital tools to speed up scheduling and delivery, but the human research step still takes time. If your refinance is tied to a rate lock, ask whether the lock covers the appraisal period and what happens if the appraisal extends the timeline.
You generally have the right to receive a copy of the appraisal report. Review it when it arrives. Check the basic facts, such as square footage, bedroom count, and property condition notes. If something is clearly wrong, such as an incorrect lot size or a missed recent renovation, contact your lender about the process for a reconsideration of value. Appraisers and lenders have procedures for correcting factual errors, though they are not obligated to change a value simply because you disagree with it.
Costs, Preparation, and Common Surprises
Appraisal costs vary by market, property type, and loan program. A typical single-family home appraisal may fall in the several-hundred-dollar range, while complex properties can cost more. The fee is usually paid upfront or rolled into closing costs, depending on the lender. It is separate from the application fee and other closing costs, so budget for it as a distinct line item.
Preparation can help the visit go smoothly. You do not need to stage the home like a listing, but a clean, accessible property makes it easier for the appraiser to observe features and condition. Make sure the appraiser can access all rooms, the attic, the garage, and the exterior. Provide a short list of recent improvements if you have one, along with permits or receipts for major work. This information can help the appraiser account for upgrades that comparable sales may not reflect.
One common surprise is a low appraisal. If the value comes in below what you expected, the lender may reduce the loan amount, require more equity, or ask you to bring cash to closing. In some cases, you can challenge the value with a reconsideration request, but the outcome depends on the facts. Another surprise is a repair requirement. If the appraiser notes a condition that violates loan program standards, the lender may require the work to be completed before closing. Knowing these possibilities in advance helps you plan for contingencies rather than react to them.
For a broader walkthrough of the entire refinance sequence, including how applications, underwriting, and closing fit together, see this step-by-step guide to how mortgage refinancing works. It pairs well with the appraisal details here, especially if you are still deciding whether a refinance makes sense for your situation.
How the Appraisal Affects Your Loan Terms and Equity Position
The appraised value feeds directly into your loan-to-value ratio, which is one of the most important numbers in mortgage pricing. A higher value lowers your LTV, and a lower LTV can mean better pricing, fewer restrictions, and in some cases the ability to remove mortgage insurance. If you are refinancing to drop private mortgage insurance, the appraisal is often the deciding factor. The lender needs to see that your loan balance is at or below a certain percentage of the home's value.
For a cash-out refinance, the appraisal sets the ceiling on how much equity you can access. Lenders typically allow you to borrow a percentage of the appraised value, minus the existing loan balance and certain costs. If the appraisal comes in lower than expected, the available cash shrinks. If it comes in higher, you may have more room than you planned. This is one reason borrowers sometimes order an appraisal early or ask the lender about valuation estimates before committing to a cash-out strategy.
The appraisal also affects your equity position going forward. A refinance replaces your old loan with a new one, and the new loan amount is based on the value the appraiser supports. If the value is accurate, your equity is measured against a realistic number. If the value is too high, you could end up borrowing more than the home is worth, which is a risk for both you and the lender. The appraisal is a check against that outcome.
If you want to run numbers before the appraisal happens, use a payment calculator to estimate how different loan amounts and rates affect your monthly payment. A calculator will not tell you what your home is worth, but it can help you compare scenarios and decide how much the appraisal outcome matters to your plans. For general education on lending options and tools, LoanFinancing offers plain-language resources that complement the refinance process.
Final Thoughts on Navigating the Appraisal Step
Appraisal requirements for refinancing a home are a normal part of the process, not a hurdle designed to trip you up. The appraisal exists to confirm value, protect the lender's collateral, and keep the loan on solid footing. In many cases, it is a routine step with a predictable cost and timeline. In others, a waiver may remove the need entirely, or a low value may require a change of plans. The key is to ask questions early, understand your lender's specific rules, and prepare the property so the appraiser can see it clearly. With that approach, the appraisal becomes one more manageable step on the path to a refinance that fits your goals.