
Home Appraisal vs Home Inspection: Key Differences
Understand the home appraisal vs home inspection difference, from who orders each report to how the results can change your financing or your negotiation.
By Samuel Keller
You have found the house you love, negotiated a price, and signed a purchase agreement. Now comes a flurry of activity before closing, including two evaluations that sound similar but serve completely different purposes: the home appraisal and the home inspection. Confusing the two can lead to costly misunderstandings, missed negotiation opportunities, or even a failed loan. This guide breaks down the home appraisal vs home inspection difference in plain language, so you know exactly what to expect, who pays for what, and how each result can affect your purchase.
The Core Difference: Lender Protection vs Buyer Protection
The home appraisal vs home inspection difference comes down to who the evaluation serves. An appraisal exists to protect the lender's financial interest. The lender wants to confirm that the property is worth at least as much as the loan amount, because the house serves as collateral. An inspection, by contrast, exists to protect you, the buyer. It gives you a detailed picture of the property's condition so you can make an informed decision before closing.
Think of it this way: the appraisal answers the question, "Is the house worth the money the lender is lending?" The inspection answers the question, "Is the house safe and sound, and what repairs might be needed?" A home can appraise perfectly and still have a failing roof, a cracked foundation, or outdated electrical wiring. Conversely, a house can be in pristine condition but appraise below the agreed-upon sale price, which creates financing challenges.
Understanding this division of purpose is the foundation for every other difference between the two processes. The appraiser works for the lender, while the inspector works for you. Their findings are used in different ways, at different points in the transaction, and with different consequences for your wallet and your peace of mind.
Who Conducts Each Evaluation and What They Examine
Appraisers and inspectors are both licensed or certified professionals, but their training, methods, and focus areas differ significantly. Knowing what each one looks for helps you interpret their reports correctly and avoid unrealistic expectations.
The Home Appraiser
An appraiser is a state-licensed professional who estimates the market value of a property. Lenders typically order the appraisal through an appraisal management company to ensure independence. The appraiser does not work for you or the seller; they work for the lender, even though the borrower usually pays the fee.
During a visit that typically lasts 30 to 60 minutes, the appraiser measures the home, notes its features and condition, and compares it to recently sold properties in the area (comparable sales, or "comps"). The final report includes a professional opinion of value, usually expressed as a single number. Appraisers look at square footage, bedroom and bathroom count, lot size, location, upgrades, and overall condition, but they are not performing a technical inspection. They do not test appliances, inspect the roof from top to bottom, or evaluate the electrical system in detail.
The Home Inspector
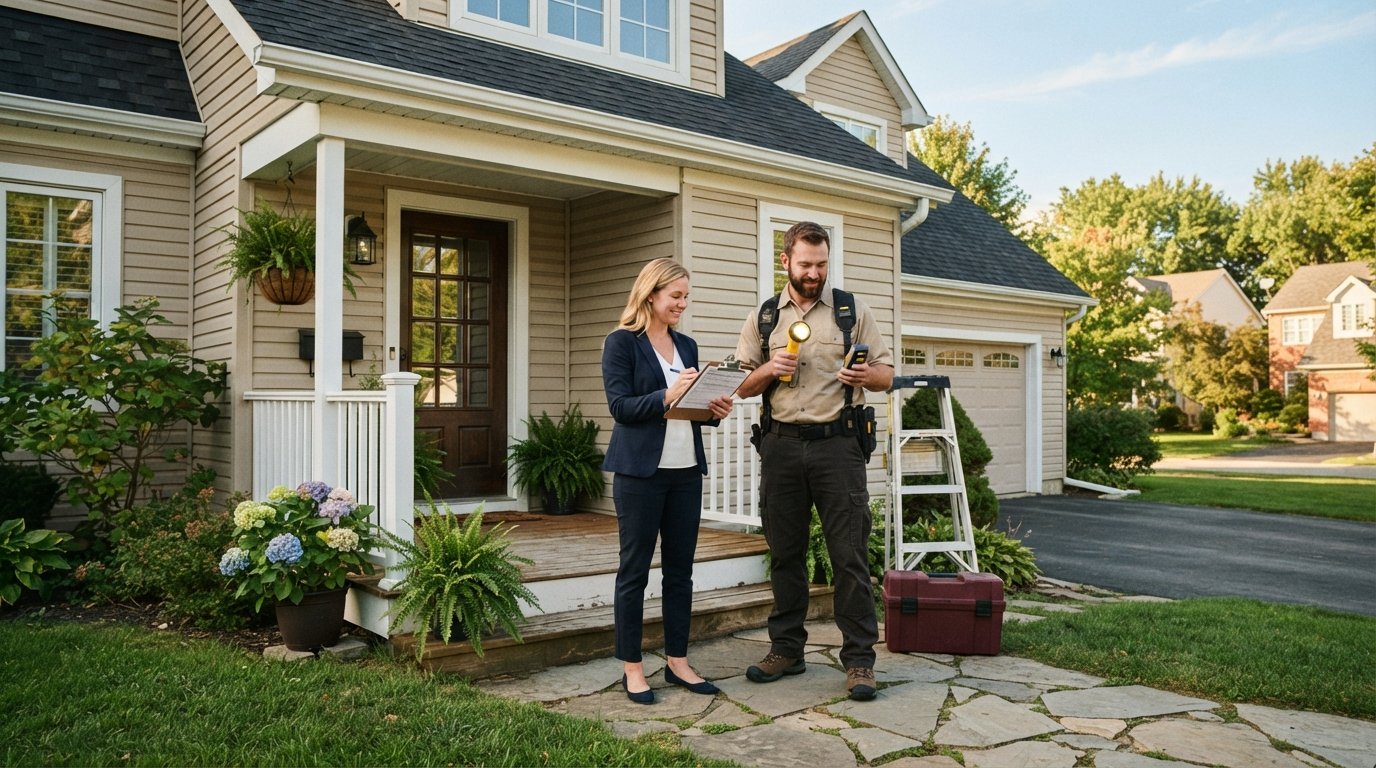
A home inspector is trained to evaluate the physical condition of the property. The inspection usually takes two to four hours, and the inspector encourages the buyer to attend. The report covers major systems and components, including the roof, foundation, attic, plumbing, electrical, heating and cooling, and visible insulation.
Inspectors do not estimate market value and do not pass or fail a house. Instead, they describe what they observe and flag items that are defective, unsafe, or near the end of their useful life. The report often includes photos and recommendations for further evaluation by specialists. Here is a quick comparison of what each professional typically examines:
- Appraiser: Market value, comparable sales, square footage, condition rating, and features that affect price.
- Inspector: Roof, foundation, plumbing, electrical, HVAC, appliances, windows, and structural components.
- Appraiser: Produces a value opinion used by the lender to approve the loan.
- Inspector: Produces a condition report used by the buyer to negotiate repairs or walk away.
Because the two reports serve different audiences, it is normal for an appraisal to say nothing about a leaky water heater and for an inspection to say nothing about whether the home is priced fairly. A complete picture of the property requires both perspectives, which is why lenders order appraisals and smart buyers order inspections.
How the Results Can Affect the Sale or Your Financing
The outcome of each evaluation can change the course of a transaction, but they trigger different consequences. An appraisal affects your loan approval and your financing terms. An inspection affects your negotiation leverage and your decision to proceed.
When the Appraisal Comes in Low
If the appraised value is lower than the purchase price, the lender will typically only lend based on the appraised value. For example, if you agreed to pay $400,000 but the home appraises at $380,000, the lender's loan-to-value calculation uses the lower number. You would need to cover the $20,000 gap in cash, renegotiate the price with the seller, or cancel the contract under your appraisal contingency.
A low appraisal is not a reflection of the home's quality; it simply means the appraiser's analysis of recent comparable sales did not support the contract price. In a fast-moving market, appraisals can lag behind rising prices, which is why appraisal contingencies matter. If you are still early in the process and want to understand the fees involved on closing day, our guide on what closing costs to expect when buying a home explains how appraisal fees fit into the broader cost picture.
When the Inspection Reveals Problems
An inspection report can reveal anything from minor maintenance items to serious structural issues. Depending on the findings and the terms of your contract, you may be able to ask the seller to make repairs, request a credit toward closing costs, renegotiate the price, or cancel the purchase and recover your earnest money. The inspection itself does not affect your loan approval, but it can affect whether you want to move forward at all.
It helps to separate findings into categories: safety issues (such as exposed wiring or a gas leak), major systems near failure (such as a roof at the end of its life), and routine maintenance (such as a dripping faucet). Sellers are more likely to address the first two categories, while the third is usually something a buyer absorbs after closing. Knowing this distinction keeps negotiations realistic.
Can You Waive an Appraisal or an Inspection?
Buyers sometimes ask whether they can skip one or both evaluations to strengthen an offer or save money. The short answer is yes, but the risks are very different for each.
Waiving the Appraisal
An appraisal waiver means you agree to proceed with financing even if the home appraises below the purchase price. Some lenders offer appraisal waivers for certain low-risk loans, and some buyers waive the appraisal contingency in competitive markets to make their offer more attractive. The risk is straightforward: if the appraisal comes in low, you must cover the difference in cash or lose the deal. Waiving the appraisal does not eliminate the lender's need for a valuation; it simply removes your protection if the value falls short.
Waiving the Inspection
Waiving the inspection is riskier in a different way. The inspection is your only opportunity to learn about the home's condition before you own it. Without it, you could inherit thousands of dollars in hidden repairs, from a failing furnace to a foundation problem that was painted over. Some buyers waive the inspection contingency but still conduct an "information-only" inspection so they know what they are buying without asking for repairs. That approach preserves knowledge while keeping the offer competitive.
In both cases, the decision should depend on your risk tolerance, your cash reserves, and the competitiveness of your market. A house that is priced well below comparable sales might justify an appraisal waiver; a house that has been sitting on the market with visible wear might justify keeping a full inspection contingency. The key is to understand what you are giving up before you sign.
Timing, Cost, and Order of Operations
Appraisals and inspections happen at different points in the transaction and are paid for by different parties. The appraisal is typically ordered by the lender after you submit your loan application and are under contract. The inspection is usually scheduled by the buyer shortly after the offer is accepted, often within a set number of days specified in the contract.
Costs vary by market and property type, but appraisals generally range from $300 to $700, while inspections typically range from $300 to $600, with larger or older homes costing more. The appraisal fee is a closing cost paid by the borrower, while the inspection fee is paid directly to the inspector, usually at the time of service. Neither fee is typically refundable if the deal falls through, which is one more reason to understand the process before scheduling.
In many transactions, the inspection happens first, sometimes before the appraisal is ordered. That order makes sense: if the inspection reveals a deal-breaker, you may want to cancel before the lender spends money on an appraisal. Communication between you, your agent, and your lender helps keep these moving parts on schedule. If you are comparing loan options for your purchase, platforms like Express Mortgage Quotes can help you understand available products and request quotes from multiple lenders, which complements the education you get from independent resources like MortgageDirectory.
Common Myths and Misunderstandings
Several persistent myths blur the home appraisal vs home inspection difference. Clearing them up prevents unpleasant surprises.
One myth is that a passing appraisal means the house is in good condition. It does not. Appraisers note obvious condition issues that affect value, but they are not inspectors and do not test systems. A house can appraise at full value with a roof that needs replacing next year.
Another myth is that the inspector works for the lender or the real estate agent. The inspector works for you, the buyer, and should be chosen independently. Similarly, some buyers believe the appraisal protects them if the home is overpriced. In reality, the appraisal protects the lender's collateral position; your protection comes from your own research and your contingencies.
Finally, there is a misconception that you can skip both evaluations if you are paying cash. A cash buyer can skip the appraisal because there is no lender, but skipping the inspection is still a gamble. The inspection is about the condition of what you are buying, and that matters regardless of how you finance it.
Distinguishing between these two evaluations also matters after you close. If you later refinance or apply for a home equity line of credit, the lender will likely order a new appraisal, but no inspection is required because you already own and occupy the home. That is why the appraisal vs inspection distinction is not just a closing-table curiosity; it is part of how mortgage lending works at every stage.
Practical Takeaways for Buyers
As you move through your purchase, keep these points in mind:
- Budget for both the appraisal fee and the inspection fee; neither replaces the other.
- Attend the inspection if possible and read the full report, not just the summary.
- Review your contract's appraisal and inspection contingencies before waiving anything.
- Use inspection findings to negotiate repairs or credits, but keep requests reasonable and documented.
- If the appraisal comes in low, discuss options with your lender before assuming the deal is dead.
Each of these steps gives you more control over a process that can feel overwhelming. The more you understand about who is evaluating what and why, the better equipped you are to ask the right questions and make decisions that protect both your finances and your future home.
In short, the home appraisal vs home inspection difference is not a technicality to gloss over. One protects the lender's investment and affects your financing; the other protects you and affects your decision. Treat them as complementary steps in the same journey, and you will enter closing with clearer eyes and fewer surprises.