
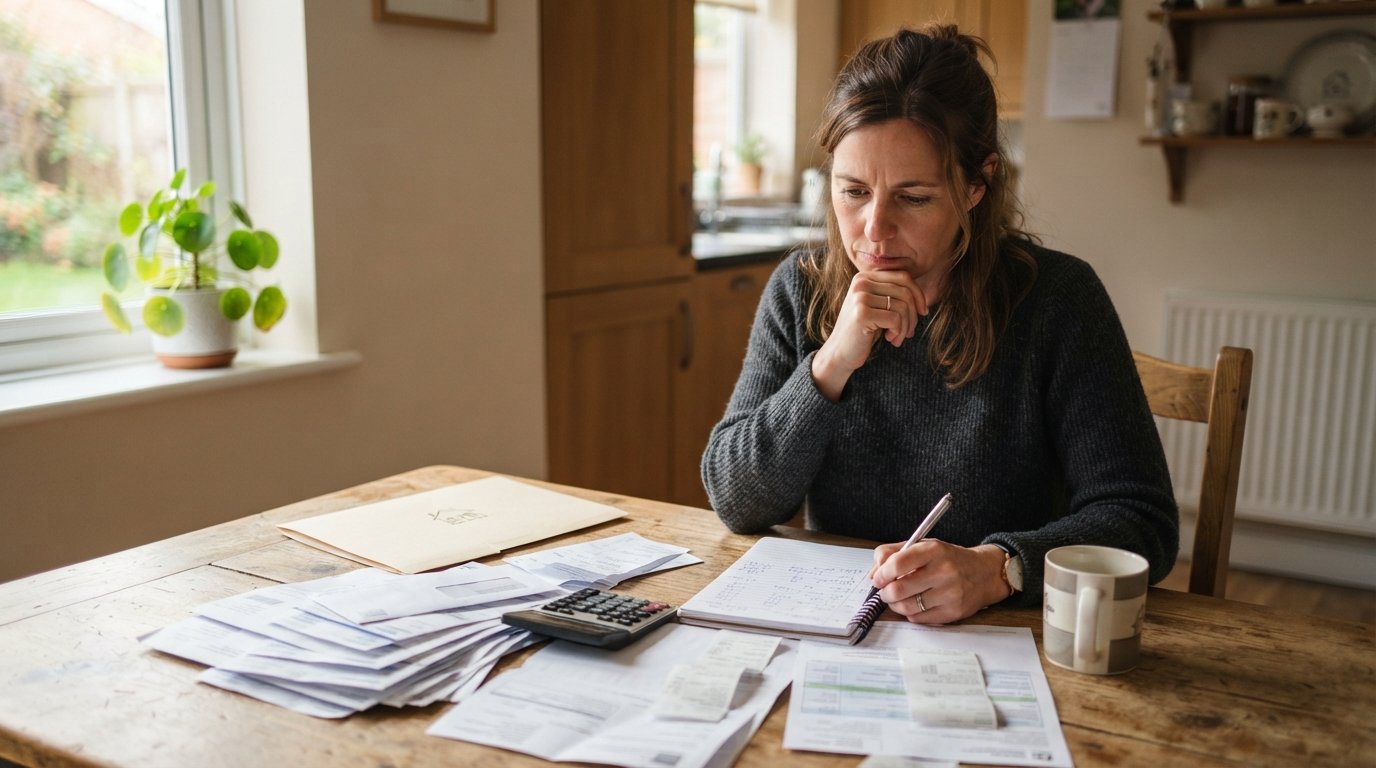
How to Budget for Homeownership Beyond the Mortgage Payment
Master how to budget for homeownership beyond mortgage payment by factoring in taxes, insurance, maintenance, and utilities to avoid surprise bills.
By Patrick Reed
Your mortgage payment is only the beginning of what you will spend as a homeowner. Property taxes, insurance, maintenance, utilities, and HOA fees can add hundreds or even thousands of dollars to your monthly outlay. Many buyers focus on principal and interest, then get blindsided by the true cost of ownership. The key to avoiding that shock is learning how to budget for homeownership beyond the mortgage payment, so you can plan for every expense and keep your finances stable.
Why the Mortgage Payment Is Just the Starting Point
When you use a mortgage calculator, the number you see often includes principal, interest, property taxes, and insurance (PITI). But even that fuller picture leaves out several recurring costs. Homeowners also pay for maintenance, repairs, utilities, HOA dues, and sometimes private mortgage insurance (PMI) or additional fees. According to housing experts, the total cost of owning a home typically runs 30 to 40 percent higher than the principal and interest payment alone. That gap is why creating a comprehensive budget is essential before you buy.
Lenders evaluate your debt-to-income ratio based on the mortgage payment, but they do not factor in the cost of a new roof or a broken water heater. As an educational resource, MortgageDirectory's guide on reverse mortgage eligibility explains how equity and age affect loan options, but the same principle applies to all mortgages: understanding the full financial commitment is critical. A realistic budget accounts for the known costs and prepares you for the unknowns.
Common Ongoing Costs Beyond Principal and Interest
Start by listing every expense that comes with your home. Some are fixed and predictable, while others vary. Here are the most common categories you need to include in your budget:
- Property taxes: Usually paid through an escrow account as part of your monthly payment, but you should verify the annual amount and any potential increases.
- Homeowners insurance: Also often escrowed, but premiums can rise after claims or due to market conditions. Budget for potential increases.
- HOA fees: If you live in a community with a homeowners association, these monthly or quarterly dues cover shared amenities and maintenance. They can range from modest to substantial.
- Maintenance and repairs: Even new homes need upkeep. The 1% rule suggests budgeting 1% of your home's value annually for maintenance.
- Utilities: Electricity, gas, water, sewer, trash, and internet are typically not included in your mortgage payment.
- Commuting costs: If you move farther from work, your transportation expenses may increase.
Each of these costs can fluctuate, so it is wise to build a buffer into your budget. For example, property taxes may increase after a reassessment, and insurance premiums can jump if you file a claim. By planning for these variations, you avoid dipping into savings or credit when bills rise.
Applying the 1% Rule for Maintenance and Repairs
The 1% rule is a simple guideline: set aside 1% of your home's purchase price each year for maintenance and repairs. For a $300,000 home, that means $3,000 annually, or $250 per month. This fund covers routine tasks like painting, landscaping, and servicing HVAC systems, as well as unexpected repairs like a leaking roof or a broken appliance. While the 1% rule is not perfect for every situation (older homes may need more, newer homes less), it provides a starting point.
To make this work, treat your maintenance fund like a bill. Set up a separate savings account and transfer the monthly amount automatically. When a repair arises, you will have the cash ready and avoid putting it on a credit card. Over time, you can adjust the percentage based on your home's age and condition. For example, a 50-year-old house might require 2% or more, while a brand-new construction may need less than 1% in the early years.
Estimating Utility and Commuting Costs
Utilities and commuting are often overlooked, yet they can significantly impact your monthly budget. Before you buy, ask the seller or real estate agent for average utility bills from the past year. If that information is not available, use online calculators or ask neighbors. Consider the size of the home, the local climate, and the energy efficiency of appliances. For instance, a larger home in a hot climate will have higher cooling costs.
Commuting costs include fuel, public transit fares, parking, and vehicle wear and tear. If you move to a suburb with a longer drive, your transportation expenses may rise. Use a commuting calculator or track your current spending and adjust for the new distance. Also factor in tolls and potential changes to your car insurance if your mileage increases. These costs add up quickly, so include them in your budget from the start.
Creating a Realistic Monthly Budget That Includes Savings
Now that you have identified all the costs, it is time to build a monthly budget. Start with your net income, then subtract your mortgage payment (including escrow items). Next, allocate funds for the ongoing costs listed above. Do not forget to include savings goals, such as an emergency fund and retirement contributions. A common recommendation is to save at least three to six months of living expenses in an emergency fund, and homeownership makes this even more important.
Here is a step-by-step framework to create your budget:
- Calculate your total monthly housing costs: Add principal, interest, property taxes, insurance, HOA fees, and any PMI.
- Add maintenance and repairs: Use the 1% rule or a customized estimate.
- Estimate utilities and commuting: Use historical data or conservative estimates.
- Include savings: Allocate a portion of your income to an emergency fund, home repair fund, and other financial goals.
- Review and adjust: Compare your total expenses to your income. If the numbers are tight, look for areas to cut back or consider a less expensive home.
After building your budget, stress-test it. What if property taxes rise 10 percent? What if you need a new roof in two years? Having a buffer in your savings account can prevent financial strain. Also, consider setting up separate accounts for different goals (e.g., one for maintenance, one for emergencies) to keep your finances organized.
Tools and Resources to Simplify Budgeting
Fortunately, you do not have to do all this math alone. MortgageZone offers a range of mortgage calculators and educational guides that can help you estimate payments and understand loan terms. While MortgageDirectory does not quote rates or take applications, its payment calculator can show you the breakdown of principal, interest, taxes, insurance, and HOA, giving you a head start on your budget. Combine these tools with your own research to create a personalized plan.
Additionally, many financial apps allow you to track spending and set savings goals. Use them to monitor your actual expenses versus your budget, and adjust as needed. The more informed you are, the better equipped you will be to handle the financial responsibilities of homeownership.
Avoiding the Most Common Budgeting Mistakes
Even with the best intentions, homeowners often make budgeting errors. One common mistake is underestimating maintenance costs, especially in the first year when unexpected repairs can pop up. Another is forgetting to account for rising property taxes or insurance premiums. Some buyers stretch their budget to the maximum mortgage approval, leaving no room for savings or emergencies. To avoid these pitfalls, be conservative in your estimates and leave a cushion.
Also, do not neglect the cost of furnishing and decorating your new home. These one-time expenses can add up quickly. Plan for them in your initial budget or spread them out over time. Finally, remember that your income and expenses may change. Review your budget annually and after major life events to ensure it still aligns with your goals.
Budgeting for homeownership beyond the mortgage payment requires diligence and planning, but it pays off in financial stability and peace of mind. By accounting for all the costs and building a realistic budget, you can enjoy your home without worrying about surprise bills. Start with the steps outlined here, use available tools, and adjust as you go. Your future self will thank you.