
How to Save for a Down Payment Fast: 7 Proven Strategies
Learn how to save for a down payment fast with proven strategies like automating savings, using windfalls, and exploring assistance programs. Start today.
By Julia Griffin
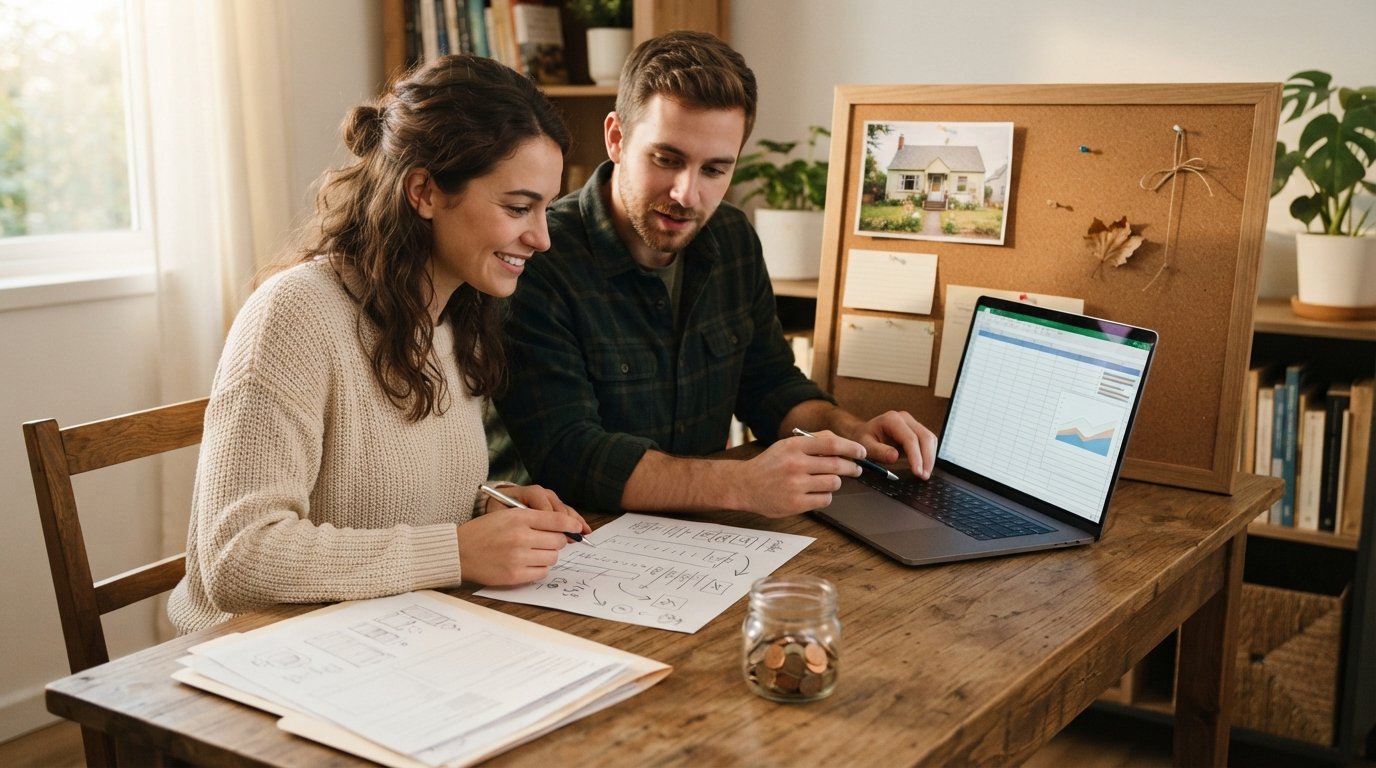
Saving for a down payment can feel like a race against rising home prices, especially when you are eager to buy. But with a focused plan and a few smart tactics, you can accelerate your savings and reach your goal faster than you might think. Whether you are a first-time buyer or looking to move up, the key is to combine disciplined saving with strategic use of available resources. In this guide, we will walk you through practical steps to save for a down payment quickly, while keeping your financial health intact.
Set a Realistic Target Based on Your Loan Type
Before you start saving, you need to know exactly how much you need. The down payment requirement varies by loan type and lender. Conventional loans often require 20% down to avoid private mortgage insurance (PMI), but many lenders offer programs with as little as 3% or 5% down. FHA loans allow down payments as low as 3.5% for qualified buyers, and VA loans may require no down payment at all for eligible veterans. Understanding these options can help you set a target that fits your situation. For a deeper dive into down payment requirements, see our guide on how much down payment you need for a house.
Once you know the percentage, calculate the dollar amount based on your desired home price. For example, a 10% down payment on a $300,000 home is $30,000. Add closing costs (typically 2% to 5% of the loan amount) to your target so you are not caught short at the finish line. Setting a clear, specific goal makes it easier to track progress and stay motivated.
Automate Your Savings and Harness Windfalls
Consistency is the cornerstone of fast saving. Set up automatic transfers from your checking account to a dedicated high-yield savings account on each payday. Treating your down payment savings like a non-negotiable bill ensures you contribute regularly without relying on willpower. Even small, frequent deposits add up quickly. Aim to save a fixed percentage of each paycheck, and increase that amount whenever you get a raise or bonus.
Windfalls, such as tax refunds, work bonuses, or inheritance, can significantly boost your down payment fund. Instead of spending them, direct at least half (or all) toward your goal. For instance, a $5,000 tax refund could shave months off your timeline. Similarly, consider selling unused items, taking on a side gig, or cutting discretionary expenses temporarily to free up extra cash. The key is to prioritize your down payment over non-essential spending.
Explore Down Payment Assistance Programs and Grants
Many homebuyers overlook down payment assistance (DPA) programs that can provide grants, low-interest loans, or forgivable loans to cover part or all of the down payment. These programs are often offered by state and local housing agencies, nonprofits, and sometimes lenders. Eligibility is typically based on income, location, and buyer status (e.g., first-time buyer).
To find programs in your area, start with your state's housing finance agency website or consult a HUD-approved housing counselor. Some programs also offer closing cost assistance. Keep in mind that DPA programs may have requirements such as completing a homebuyer education course or maintaining the home as your primary residence for a certain period. Researching these options early can reduce the amount you need to save from your own funds.
Balance Your Down Payment Goal with Emergency Savings and Closing Costs
While it is tempting to pour every extra dollar into your down payment, remember that homeownership comes with ongoing expenses and unexpected repairs. Draining your emergency fund to buy a house is risky. Aim to maintain at least three to six months' worth of living expenses in an emergency fund, separate from your down payment savings. If your timeline is tight, consider a smaller down payment (if your loan program allows) to preserve cash reserves.
Also, do not forget closing costs. These include lender fees, title insurance, appraisal fees, and prepaid items like property taxes and homeowners insurance. Closing costs typically range from 2% to 5% of the purchase price. Factor them into your savings goal so you are not scrambling at the last minute. A balanced approach ensures you are financially prepared for both the purchase and the responsibilities of homeownership.
Accelerate Your Savings with These Tactics
In addition to the strategies above, consider these methods to speed up your down payment savings:
- Open a high-yield savings account: Earn more interest on your savings compared to a traditional account. Even a 1% higher APY can add hundreds of dollars over a year.
- Reduce housing costs temporarily: Move to a cheaper apartment, get a roommate, or negotiate your rent to free up more cash for savings.
- Cut recurring expenses: Cancel unused subscriptions, dine out less, and shop for better rates on insurance and utilities.
- Take on a side hustle: Freelance, deliver groceries, or monetize a hobby to generate extra income dedicated solely to your down payment.
- Use a savings challenge: Try a structured challenge like saving $5,000 in 52 weeks, where you save increasing amounts each week.
For more tools and educational resources to understand mortgage costs and plan your purchase, visit MortgageZone, a comprehensive online resource for mortgage information and guidance.
Stay Motivated and Review Your Plan Regularly
Saving for a down payment is a marathon, not a sprint, but with focus, you can pick up the pace. Review your budget and savings progress monthly. Adjust your target as needed based on changes in income or home prices. Celebrate milestones to stay motivated. Remember, the faster you save, the sooner you can achieve your goal of homeownership. With discipline and the right strategies, you can turn your dream into a reality.