
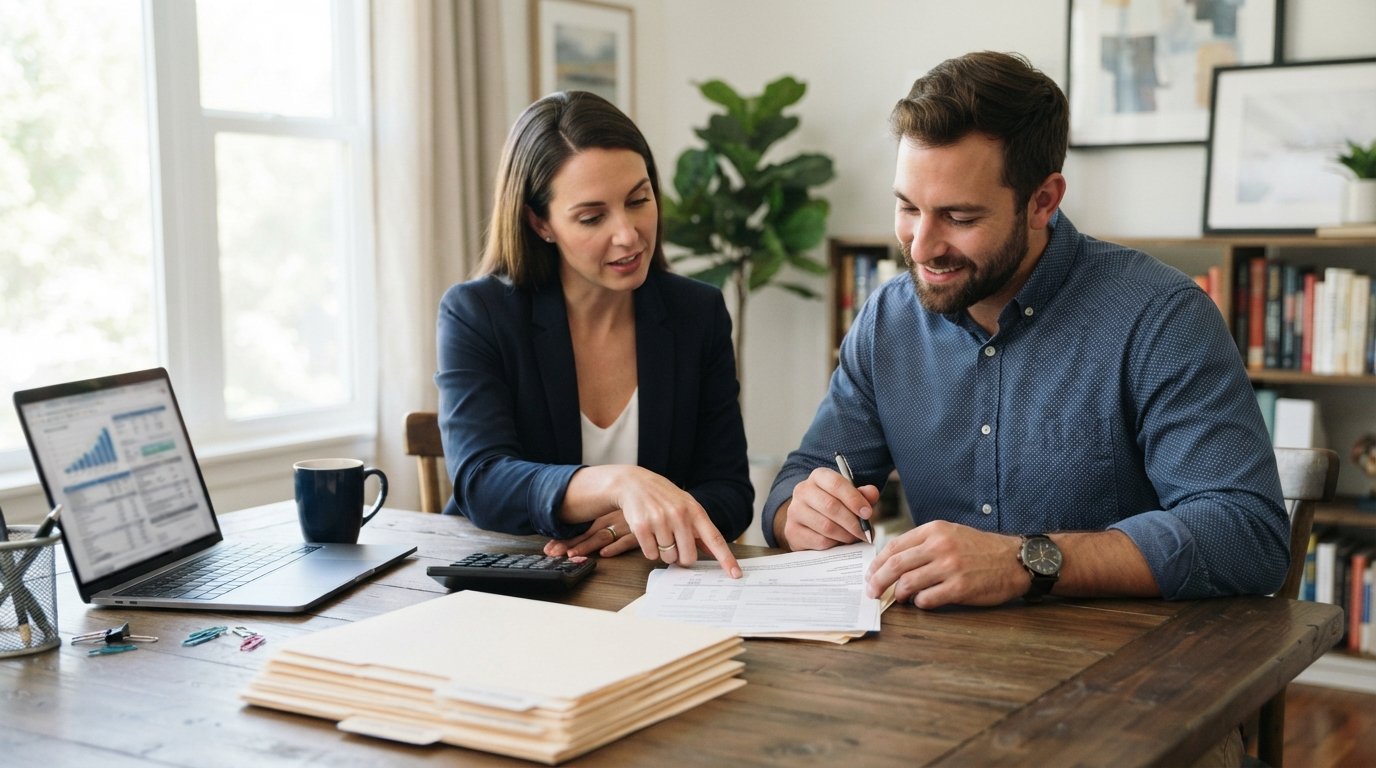
Mortgage Pre Approval Process Steps Explained Clearly
Mortgage pre approval process steps explained in plain language, from documents to credit checks, so you can shop with confidence and a stronger offer.
By Julia Griffin
You have found the house of your dreams, or you are just starting to scroll through listings, and suddenly the word "pre-approval" appears everywhere. Real estate agents ask for it, sellers expect it, and online calculators hint that it is the key to unlocking your home search. But what actually happens behind the scenes? The mortgage pre approval process steps explained here will walk you through each stage in plain language, so you can move forward with confidence instead of confusion.
Pre-approval is not a mysterious stamp of approval from a bank. It is a documented, lender-issued estimate of how much you can borrow based on verified financial information. Unlike a casual conversation with a loan officer, pre-approval involves paperwork, a credit check, and underwriting review. Understanding the sequence helps you avoid delays, present a stronger offer, and know exactly what to expect before you commit to a home purchase.
Pre-Qualification vs. Pre-Approval: What Is the Real Difference?
Many buyers use these terms interchangeably, but they describe two very different levels of verification. A pre-qualification is typically a quick, informal estimate. You might provide basic income and debt figures over the phone or through an online form, and the lender gives you a rough borrowing range without pulling your credit or reviewing documents. It is useful for early budgeting, but it carries little weight with sellers because nothing has been verified.
Pre-approval is a more rigorous process. The lender collects documentation, pulls your credit report, and runs your file through an automated underwriting system. The result is a conditional commitment: the lender has reviewed your finances and is willing to lend up to a specific amount, subject to final verification of the property and your continued financial stability. This distinction matters because real estate agents and sellers treat a pre-approval letter as credible evidence that you can actually close on a home.
For educational purposes, think of pre-qualification as a handshake and pre-approval as a signed letter of intent. Both have value, but only one carries real negotiating power in a competitive market. If you are serious about buying, aim for pre-approval before you start scheduling showings.
The Mortgage Pre Approval Process Steps Explained in Order
The pre-approval process generally follows a predictable sequence. While every lender has its own timeline and paperwork, the core steps remain consistent. Below is a numbered walkthrough of what typically happens from your first inquiry to receiving a pre-approval letter.
- Choose a lender and complete an application. You will provide basic personal information, including your name, address, Social Security number, employment history, and income details. Many lenders offer online applications, and some allow you to upload documents directly.
- Submit financial documentation. The lender will request pay stubs, W-2s or tax returns, bank statements, and information about other assets or debts. Self-employed borrowers may need additional paperwork such as profit and loss statements or business tax returns.
- Authorize a credit check. The lender pulls your credit report to review your score, payment history, and existing debts. This is a hard inquiry, which may temporarily affect your credit score, but multiple mortgage inquiries within a short window are often treated as a single inquiry by scoring models.
- Undergoing automated underwriting. Your file is run through an underwriting system that evaluates your debt-to-income ratio, credit profile, and assets. The system produces a recommendation that the lender's underwriter reviews.
- Receive a conditional approval and address conditions. The lender may issue a pre-approval letter with conditions, such as providing a gift letter for down payment funds or explaining a recent credit inquiry. Satisfying these conditions strengthens your position.
- Obtain your pre-approval letter. Once conditions are met, the lender issues a formal letter stating the approved loan amount, loan type, and expiration date. You can share this letter with real estate agents and sellers.
Each step builds on the previous one, and skipping documentation can slow the process. A common mistake is underestimating how long it takes to gather tax returns or wait for a payroll department to issue a verification of employment. Starting early and keeping digital copies of your financial documents organized will make the process smoother.
Documents You Will Need for Pre-Approval
Lenders want to see a complete picture of your financial life. The exact list varies by loan program and employment type, but most pre-approval applications require the following categories of documentation.
- Income verification: Recent pay stubs covering at least 30 days, W-2 forms from the past two years, and federal tax returns if you have self-employment income, rental income, or other non-W-2 earnings.
- Asset verification: Bank statements for checking and savings accounts, retirement account statements, and documentation for any gift funds you plan to use for a down payment.
- Credit and debt information: Authorization for a credit check, plus explanations for any recent credit inquiries or derogatory marks if requested by the lender.
- Identity and employment: Government-issued identification, proof of address, and employment verification such as a job offer letter if you are starting a new position.
Self-employed borrowers and those with variable income should expect additional scrutiny. Lenders may ask for year-to-date profit and loss statements, business licenses, or letters from accountants. Having these documents ready before you apply reduces back-and-forth and helps the underwriter move faster.
It is also wise to avoid major financial changes during the pre-approval window. Opening new credit cards, changing jobs, or making large transfers between accounts can raise questions and potentially alter your approval status. Keep your financial profile stable until you close.
How Long Does Pre-Approval Last, and When Should You Renew?
Most pre-approval letters remain valid for 60 to 90 days, though some lenders issue them for 120 days. The expiration date is not arbitrary: it reflects how quickly credit reports, income verification, and asset statements can become stale. A lender wants to confirm that your financial situation has not materially changed since the initial review.
If your home search extends beyond the expiration date, you will need to renew or refresh your pre-approval. Renewal usually involves updating your documentation, such as providing newer pay stubs and bank statements, and authorizing another credit check. Some lenders offer a streamlined renewal process for existing applicants, while others require a full re-application. Either way, do not let your pre-approval lapse while you are actively making offers, because sellers may view an expired letter as a sign that your financing is uncertain.
Timing your pre-approval strategically can save you effort. If you plan to house hunt for several months, consider starting the process closer to when you are ready to make offers. On the other hand, getting pre-approved early helps you understand your budget and identify any credit issues that need attention before you fall in love with a home you cannot finance.
How Pre-Approval Affects Home Shopping and Offers
Pre-approval changes the dynamics of home shopping in several practical ways. First, it gives you a verified price range, which prevents you from touring homes that are outside your borrowing capacity. This saves time and reduces emotional attachment to properties you cannot afford. Second, it signals to real estate agents that you are a serious buyer, which can lead to more responsive service and priority scheduling for showings.
When you submit an offer, a pre-approval letter accompanies your purchase contract. Sellers often compare offers based on financing strength, and a pre-approved buyer is generally viewed as less likely to encounter financing contingencies or last-minute loan denials. In competitive markets, some sellers may prioritize pre-approved buyers over those who are only pre-qualified or not pre-approved at all.
However, pre-approval is not a guarantee of final loan approval. The lender will still verify the property appraisal, title, and your continued financial eligibility. If you change jobs, take on new debt, or the home appraises below the purchase price, your final approval could be affected. Understanding this distinction helps you set realistic expectations and avoid surprises during the closing process.
For readers who want to explore mortgage concepts further, resources like MortgageZone offer educational guides and calculators that complement the pre-approval process. MortgageZone provides plain-language explanations of loan types, payment estimates, and refinancing options, which can be helpful as you prepare to speak with a lender.
Common Mistakes to Avoid During Pre-Approval
Even well-prepared buyers can stumble during the pre-approval stage. One frequent error is applying for pre-approval with multiple lenders without understanding how credit inquiries are handled. While mortgage inquiries within a 14- to 45-day window are typically treated as one inquiry by major scoring models, applying outside that window can ding your score. Another mistake is providing incomplete documentation, which prolongs the process and may cause the lender to issue a lower approval amount than you expected.
Buyers also sometimes confuse pre-approval with a final commitment and make irreversible decisions, such as waiving financing contingencies in an offer. A pre-approval letter is conditional, and waiving contingencies can put your earnest money at risk if the loan does not close. Always discuss contingency terms with your real estate agent and lender before submitting an offer.
Finally, avoid the temptation to make large purchases or open new credit lines after receiving pre-approval. Lenders often re-check your credit and employment before closing, and a new car loan or furniture financing can push your debt-to-income ratio above the threshold used in your approval. Keeping your financial profile steady is one of the simplest ways to protect your pre-approval status.
Frequently Asked Questions About Pre-Approval
Does pre-approval guarantee I will get a mortgage?
No. Pre-approval is a conditional commitment based on the information you provide and the lender's review at that point in time. Final approval depends on the property appraisal, title review, and verification that your financial situation has not changed. Think of pre-approval as a strong indicator, not a guarantee.
Will pre-approval hurt my credit score?
A pre-approval typically involves a hard credit inquiry, which can cause a small, temporary dip in your score. However, mortgage inquiries within a short shopping window are usually grouped together by scoring models, so comparing multiple lenders is less damaging than it might seem. The long-term benefit of knowing your borrowing range often outweighs the minor short-term effect.
Can I get pre-approved if I am self-employed?
Yes, but expect more documentation. Lenders will likely ask for two years of tax returns, year-to-date profit and loss statements, and possibly business licenses or letters from accountants. Self-employed borrowers with stable, documented income can qualify for pre-approval, though the process may take longer than for W-2 employees.
What is the difference between pre-approval and final approval?
Pre-approval estimates how much you can borrow based on your finances. Final approval occurs after the lender reviews the property, title, and all conditions, and confirms that your financial situation remains unchanged. Final approval is the green light to close; pre-approval is the green light to shop.
Understanding the mortgage pre approval process steps explained above gives you a roadmap for the early stages of home buying. From choosing a lender and assembling documents to interpreting your pre-approval letter and knowing when to renew, each step builds toward a smoother transaction. With the right preparation and a clear sense of what lenders look for, you can approach your home search with confidence and a stronger negotiating position.