
Reverse Mortgage Counseling: What to Expect in Your Session
Reverse mortgage counseling session what to expect: an independent HUD-approved counselor reviews costs, risks, and alternatives before you apply.
The letter from the lender says your reverse mortgage application is moving forward, but first there is one step you cannot skip: the counseling session. For many homeowners, this requirement feels like a hurdle, yet it is actually the most protective part of the entire process. Understanding what happens during that session removes the anxiety and helps you use the time to ask the questions that matter for your retirement. This guide walks through the purpose, the people involved, the questions you will hear, and the limits of what counseling can and cannot do.
Why Independent Counseling Is Required Before You Apply
Reverse mortgages, particularly Home Equity Conversion Mortgages (HECMs) backed by the Federal Housing Administration, carry a mandatory counseling requirement written into federal law. The rule exists because reverse mortgages are complex. Unlike a traditional forward mortgage, where you pay the lender each month and watch the balance shrink, a reverse mortgage pays you and the balance grows over time. That inversion of the usual logic is easy to misunderstand, and misunderstanding it can lead to foreclosure, lost equity, or a failed retirement plan.
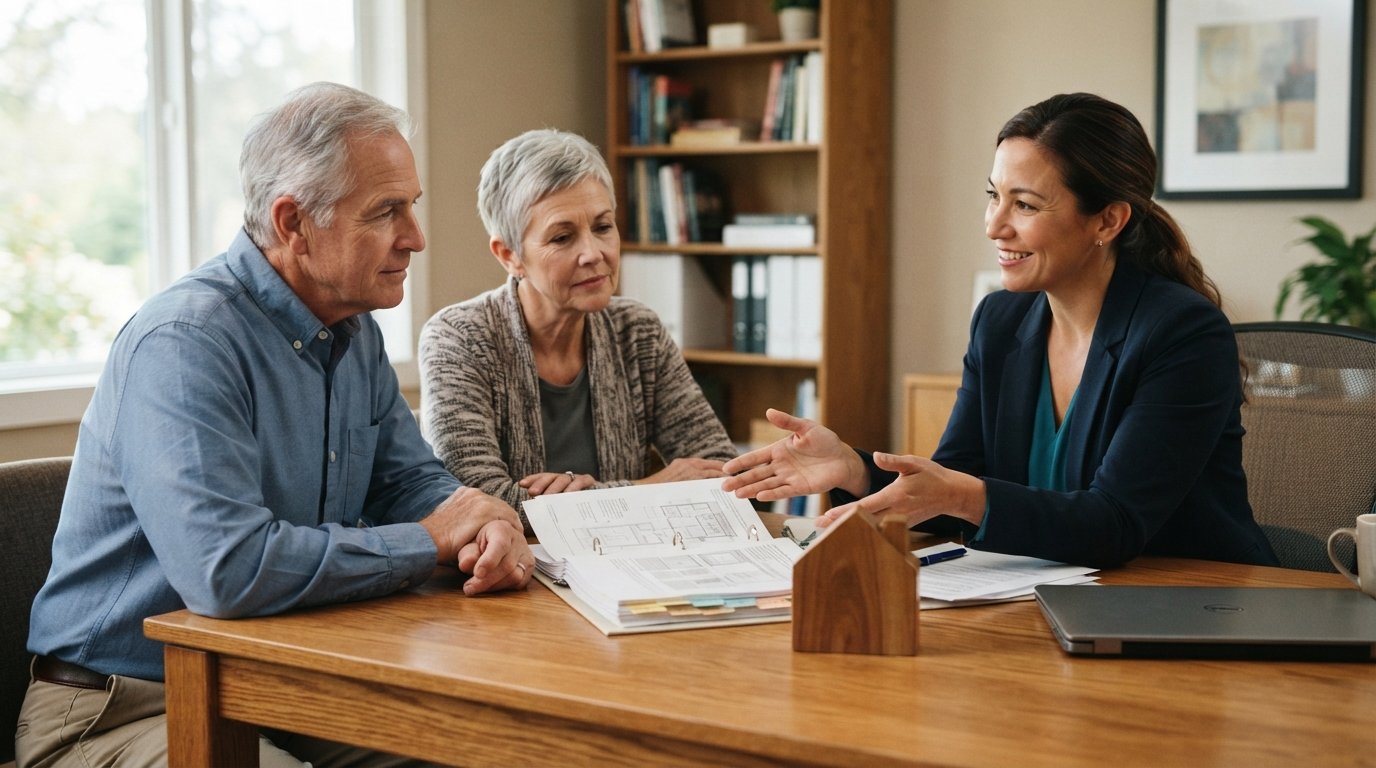
Congress and HUD designed the counseling step as a consumer safeguard. A counselor who has no financial stake in whether you close the loan reviews your situation, explains alternatives, and confirms you understand the obligations that come with the product. The session is not a sales pitch and not a rubber stamp. It is a structured conversation intended to catch problems early, whether that means a borrower who does not realize property taxes and insurance remain their responsibility or a homeowner who has not compared a reverse mortgage against a home equity loan or a downsizing move.
One detail surprises many applicants: the counseling must happen before you submit a formal application, not after. Lenders will require a certificate proving you completed the session, and some will not process the file without it. If you are still weighing whether a reverse mortgage fits your plan, the counseling requirement is a natural point to pause and review the choices. Our guide on types of reverse mortgages explains how HECM, proprietary, and single-purpose loans differ, which is useful context before your session.
Who Provides the Counseling and How It Is Delivered
The counselor you meet with must be approved by HUD and typically works for an independent nonprofit or public agency, not for the lender. This independence is the point. The counselor's job is to educate, not to close a loan, and they cannot steer you toward a particular lender or product. HUD maintains a search tool that lists approved counselors by state and ZIP code, and the lender must provide a list of referral sources as well.
Delivery comes in several formats, and you can usually choose the one that suits you. The most common options include:
- In-person sessions at a local counseling agency, often the best choice if you prefer face-to-face conversation and help with paperwork.
- Telephone counseling scheduled in advance, which works well for homeowners in rural areas or with limited mobility.
- Video sessions offered by some agencies, combining the convenience of remote delivery with visual aids and document sharing.
Each format carries the same core content and the same certificate at the end. Sessions typically last 60 to 90 minutes, though they can run longer if you have many questions or a complicated situation such as a trust-held property or a non-borrowing spouse. Some agencies charge a small fee, often around $125, and HUD rules allow that fee to be paid from loan proceeds in many cases. If cost is a barrier, ask about fee waivers, since many agencies offer them for low-income borrowers.
Before the session, gather documents that help the counselor understand your finances: recent mortgage statements, property tax bills, homeowner insurance declarations, Social Security and pension statements, and any information about other debts. You do not need a perfect file, but the more the counselor knows, the more useful the conversation becomes.
The Questions a Counselor Will Typically Cover
Every counseling session follows a similar arc, moving from your goals to the mechanics of the loan to the risks and alternatives. The counselor will ask about your reasons for considering a reverse mortgage. Are you trying to eliminate a monthly mortgage payment, cover medical costs, fund home repairs, or create a cushion for unexpected expenses? The answer shapes the rest of the conversation, because a reverse mortgage is a poor fit for some goals and a reasonable fit for others.
Expect a thorough review of how the loan actually works. The counselor will explain that you remain the homeowner, that you must keep paying property taxes, homeowner insurance, and HOA dues, and that failing to do so can lead to foreclosure. They will cover the difference between fixed and adjustable rates, the meaning of a line of credit that grows over time, and how the loan balance rises as interest and fees accrue. They will also walk through the non-recourse feature, which caps what you or your heirs owe at the value of the home, and the rules about living in the home as your principal residence.
Alternatives are a required part of the discussion. The counselor will compare a reverse mortgage against options such as selling and downsizing, a traditional home equity loan or HELOC, a cash-out refinance, government assistance programs, or simply budgeting differently. This is not an attempt to talk you out of the loan. It is an attempt to make sure you have considered the cheapest or least risky path first. The session also covers costs: origination fees, mortgage insurance premiums, servicing fees, and closing costs, along with the fact that these can be financed into the loan rather than paid upfront.
Finally, the counselor will confirm your understanding and issue the certificate. Some agencies follow up with a written summary. If you finish the session and realize you still have questions, you can schedule another appointment, and there is no penalty for taking extra time before applying.
What Counseling Does Not Do: No Approval, No Guarantee
A common misconception is that completing counseling means you are approved or that the loan is guaranteed. Neither is true. Counseling is an educational requirement, not an underwriting decision. The lender still evaluates your credit, income, property condition, and ability to pay taxes and insurance, and the lender can decline the application even after you hold a valid certificate.
The certificate also does not lock in a rate, a loan amount, or a set of terms. Those come later in the process and depend on the lender, the appraised value of your home, and current market conditions. Nor does counseling constitute financial, tax, or legal advice. The counselor explains the product, but decisions about whether a reverse mortgage fits your retirement plan belong to you, ideally with input from a financial planner or attorney.
What counseling does provide is a documented record that you received independent education before committing to a complex loan. That record protects you if a dispute arises later and gives you a natural checkpoint to reconsider. If you are comparing reverse mortgage options with other ways to tap home equity, the educational resources at Express Mortgage Quotes can help you see how lenders present these products side by side.
How to Get the Most From Your Session
The homeowners who benefit most from counseling treat it as a two-way conversation rather than a formality. Arrive with a written list of questions, take notes, and do not hesitate to ask the counselor to slow down or repeat an explanation. If you are married, both spouses should attend, even if only one is listed as a borrower, because the non-borrowing spouse needs to understand the rules about remaining in the home.
Ask specifically about the scenarios that worry you. What happens if you need to move into assisted living? What happens if your home value drops? How does the loan get repaid, and what are your heirs' options? A good counselor welcomes these questions and answers them in plain language. If you feel rushed or the counselor cannot explain a concept clearly, you are allowed to pause the session and reschedule with a different agency.
After the session, review the certificate and any written materials while the conversation is fresh. Compare what you learned against your original goals. If the numbers do not work or the risks feel too large, you can walk away, and nothing about counseling obligates you to proceed. That freedom is the entire purpose of the requirement.
Reverse mortgage counseling is best understood as a built-in second opinion, one that costs little and can save a homeowner from a costly mistake. Go in prepared, ask direct questions, and use the session to confirm that the loan fits your life rather than the other way around.