
Reverse Mortgage Financial Assessment: What Lenders Review
See exactly what income, credit, and expense factors lenders examine during a reverse mortgage financial assessment, and how set-asides protect your loan.
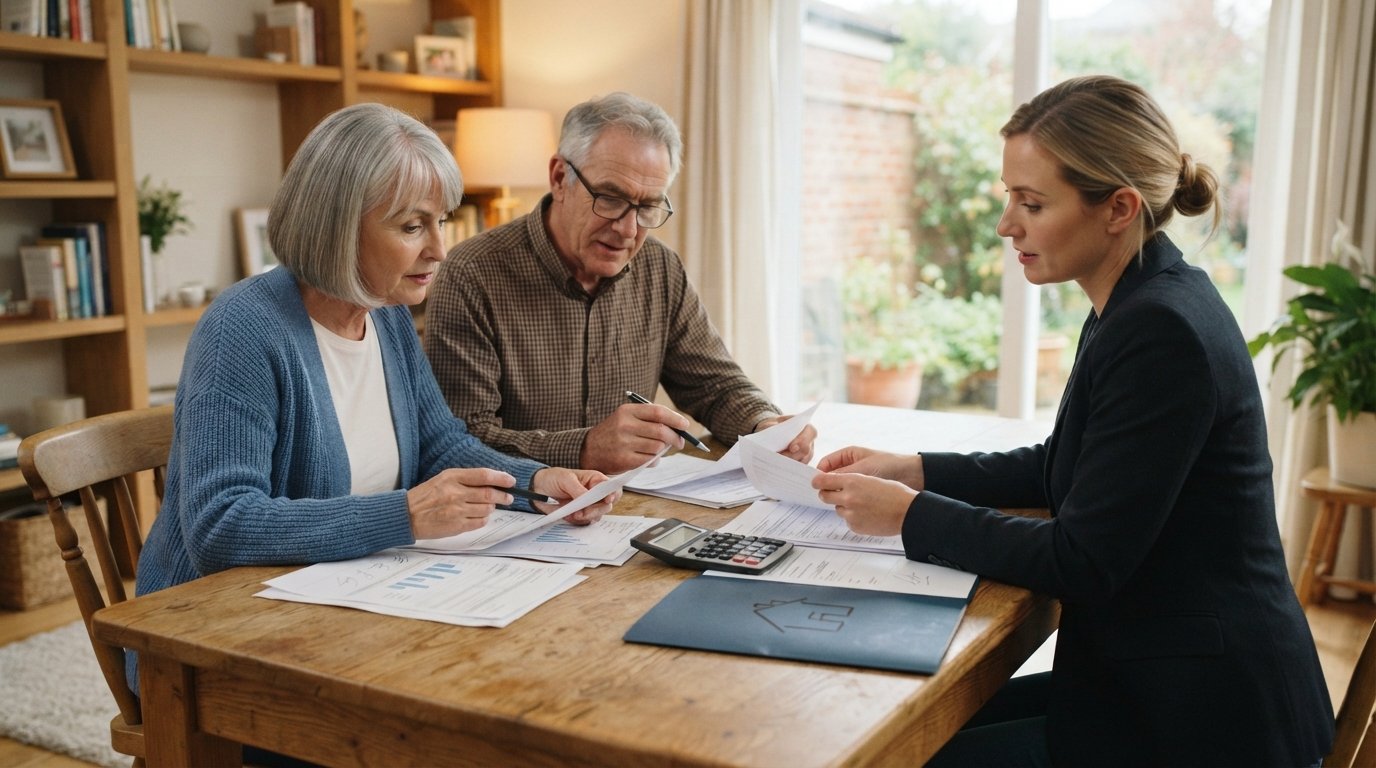
A reverse mortgage can turn home equity into retirement cash flow, but before any lender approves one, it runs a financial assessment. This review is not a formality. It determines whether you can afford ongoing property charges and whether the loan can be structured to protect both you and the lender. Understanding exactly what lenders examine during this process helps you prepare, avoid surprises, and make informed decisions about your retirement finances. The assessment focuses on income, credit, expenses, and the set-aside options available to cover future obligations.
Why Lenders Conduct a Financial Assessment
The financial assessment exists to answer one central question: can you keep up with the costs that come with owning a home, even after the reverse mortgage closes? With a traditional forward mortgage, the lender checks income and credit to see if you can repay the loan. A reverse mortgage works differently because the loan balance grows over time and typically is not repaid until the last borrower moves out or passes away. But the borrower still must pay property taxes, homeowners insurance, and maintain the home. If those obligations fall behind, the loan can go into default and eventually become due. The financial assessment is designed to reduce that risk.
Lenders use the assessment to verify that you have the capacity and willingness to meet these ongoing obligations. The review happens after you pass the age eligibility threshold, which is 62 for most reverse mortgage products. Passing the age test does not guarantee approval. The financial assessment adds a second layer of scrutiny, looking at your income stability, credit history, and monthly expenses. If weaknesses appear, the lender may require a set-aside (a portion of your loan proceeds reserved to pay taxes and insurance) or may decline the application entirely. Understanding this sequence helps you see why some applicants who meet the age requirement still face hurdles.
The assessment also supports new borrower protections introduced in recent years. Lenders must follow guidelines that require them to evaluate your ability to pay property charges and to document their findings. This means the process is more standardized than in the past, but it also means more paperwork and more questions. Preparing ahead of time can make the experience smoother and reduce the chance of delays.
Income and Credit: What Lenders Verify
Income verification is a core part of the financial assessment. Lenders want to see that you have reliable money coming in to cover everyday living expenses and property charges. They typically review sources such as Social Security, pensions, annuities, investment income, and employment income if you are still working. Documentation usually includes recent bank statements, benefit award letters, tax returns, and pay stubs. The lender is not just looking at the amount; it also considers stability and whether the income is likely to continue.
Credit history also matters, but not in the same way as a forward mortgage. Lenders review your credit report to see how you have handled past obligations, particularly housing-related payments. A history of late property tax or insurance payments can raise concerns. However, a less-than-perfect credit score does not automatically disqualify you. The lender may weigh the credit findings alongside other factors, such as cash reserves or the option of a set-aside. The goal is to identify patterns that suggest a risk of future default on property charges.
Here are the common document categories lenders request during the financial assessment:
- Proof of income: Social Security statements, pension letters, annuity statements, and recent tax returns
- Bank and investment account statements for the past two to three months
- Credit report authorization and any explanation letters for negative items
- Property tax bills and homeowners insurance declarations
- Documentation of any set-aside or reserve accounts
After reviewing these documents, the lender calculates a residual income figure. This is the money left over after covering estimated living expenses and property charges. If residual income is too low, the lender may require a set-aside to cover future taxes and insurance. The set-aside is not a penalty; it is a reserve that ensures those bills get paid even if your income changes. Lenders may also look at your payment history on any existing mortgages or home equity lines of credit, because those patterns offer clues about how you manage housing debt.
Expenses, Property Charges, and Set-Asides
Expenses are the other side of the affordability equation. Lenders estimate your ongoing costs by looking at your current spending patterns and the specific costs of the home. They consider utilities, food, transportation, healthcare, and other regular bills. They also factor in the property taxes and homeowners insurance for the home that will secure the reverse mortgage. Because these charges can rise over time, lenders may project them forward using conservative assumptions. The goal is to see whether your income can comfortably cover both your living costs and the property charges.
Set-asides are a key tool lenders use to address affordability gaps. A set-aside is a portion of the loan proceeds that is reserved and used to pay property taxes and insurance on your behalf. There are two main types: a fully funded set-aside, where the lender reserves enough to cover all projected charges for the life of the loan, and a partially funded set-aside, where the borrower pays some charges directly and the lender reserves a smaller amount. The lender decides which type is appropriate based on the financial assessment. If your income is strong and your credit history is clean, you may be able to pay taxes and insurance yourself without a set-aside. If the assessment shows vulnerability, a set-aside may be required.
Understanding how set-asides work helps you plan. A set-aside reduces the amount of cash you receive at closing because those funds are earmarked for future obligations. However, it also provides peace of mind and protects you from default if your income declines or expenses rise. Lenders will explain the options and the impact on your loan proceeds. It is important to ask questions and make sure you understand how the set-aside affects your available funds and the long-term cost of the loan.
Approval Decisions and Lender Discretion
Approval decisions come from lenders, not from any government agency or educational resource. While reverse mortgage guidelines set the framework for the financial assessment, each lender applies its own underwriting standards and may interpret the rules differently. Some lenders are more conservative and require larger set-asides; others may be more flexible if you have strong compensating factors, such as significant cash reserves or a long history of on-time property tax payments. This is why shopping around and speaking with multiple lenders can be valuable.
If the financial assessment reveals weaknesses, the lender may offer alternatives. For example, you might be able to pay off some debts, add a co-borrower, or choose a different loan structure. In some cases, the lender may decline the application, but that does not mean a reverse mortgage is impossible. It may mean that a different lender or a different approach is needed. The key is to have a clear picture of your finances before you apply, so you can address issues proactively. For a deeper look at what happens if property charges are not paid, including the risk of loan maturity, see our guide on reverse mortgage tax and insurance defaults. That resource explains how defaults can accelerate the loan and what borrowers can do to avoid them.
It also helps to use educational tools to estimate your situation. A payment calculator can help you understand typical costs, but keep in mind that reverse mortgage assessments are more complex than a simple calculator. Lenders look at the full picture, including your income, credit, expenses, and reserves. For broader mortgage education and tools, you can explore resources like MortgageZone, which offers guides and calculators for various loan types. However, always remember that approval decisions rest with the lender, and no educational site can guarantee an outcome.
Preparing for the Financial Assessment
Preparation can reduce stress and improve your chances of a smooth process. Start by gathering your financial documents well in advance. Organize your income statements, bank records, tax returns, and property tax and insurance bills. Review your credit report for errors and address any issues before the lender pulls it. Consider your monthly budget and think about how a reverse mortgage fits into your overall retirement plan. If you have significant debt or irregular income, talk to a financial advisor or a reverse mortgage counselor before applying. Counseling is required for most reverse mortgages, and it can help you understand the assessment and your obligations.
Be honest and thorough in your documentation. Lenders base their decisions on the information you provide, and gaps or inconsistencies can delay or derail the process. If you have questions about what the lender will review, ask ahead of time. The loan officer or counselor can explain the specific documents required and how the assessment works. Remember that the financial assessment is not designed to be a barrier; it is a consumer protection tool that helps ensure you can stay in your home and keep the loan in good standing. By understanding what lenders review, you can approach the process with confidence and make informed choices about your retirement finances.