
USDA Loan Income Limits and Eligible Rural Areas Explained
USDA loan income limits and eligible rural areas vary by county and household size. Check both before you shop to avoid losing a home to an eligibility miss.
By Daniel Adler
Buying a home in a small town or open countryside often brings a welcome surprise: a government-backed loan program designed to make rural homeownership more affordable. The USDA loan, backed by the U.S. Department of Agriculture, offers zero down payment financing to qualified buyers in designated rural areas, but the eligibility rules around income and location trip up more applicants than almost any other part of the process. Understanding usda loan income limits and eligible rural areas before you start house hunting can save you weeks of frustration.
The core idea is straightforward. The program targets households with moderate incomes who want to live in communities that are rural in character, and it adjusts its income ceilings based on where you live and how many people share your household. The details, however, change from county to county and update annually. This guide walks through how the limits work, how to check an address, and where the program stops and your own research begins.
How USDA Loan Income Limits Are Structured
USDA income limits are not a single national number. They are set county by county, and sometimes by metropolitan area, using data tied to median household incomes in that region. The program generally caps household income at 115 percent of the area median income, though the exact figure depends on the local market and the size of your household.
This means two buyers with identical salaries could have different results depending on which side of a county line they live. A household earning $95,000 might qualify comfortably in a lower-cost rural county and fall above the ceiling in a wealthier one nearby. The USDA publishes these figures annually, and they typically rise over time as local incomes grow.
Household size is the second major variable. The program counts all adults who will live in the home and share expenses, not just the people on the loan application. A four-person household usually has a higher income ceiling than a one-person household in the same county. When you look up limits, always check the row for your actual household size rather than assuming the single-person number applies.
There is also a distinction between the direct loan program and the guaranteed loan program. Direct loans, offered through USDA's local offices, serve lower-income households and have stricter limits. Guaranteed loans, issued by approved lenders and backed by the USDA, serve moderate-income households and use the 115 percent threshold. Most buyers exploring the program are looking at the guaranteed option, but it helps to know both exist.
What Counts as Household Income
Applicants are often surprised by how much income the USDA counts. It is not just your base salary. The program looks at gross income for all household members, including overtime, bonuses, commissions, self-employment earnings, and certain forms of regular income such as Social Security or disability payments. Alimony and child support received may also be included.
Some income types are excluded or treated differently, which is why a lender or USDA office reviews pay stubs, tax returns, and employment letters rather than relying on a single number. If your income fluctuates, the reviewer typically averages recent history. If you are close to the limit, a small raise or a new side job could push you over, so it pays to check before you commit to a contract.
Here is a practical way to think about the review process:
- Gather gross income figures for every adult who will live in the home.
- Include variable pay such as bonuses and overtime, averaged over a recent period.
- Note any income that may be excluded, such as certain benefits, and ask a loan officer to confirm.
- Compare the total to the limit for your county and household size, not a neighboring county.
Because rules around income counting vary and change, treat any online calculator as a starting point rather than a verdict. The USDA's own eligibility tool and a conversation with a participating lender are the reliable next steps.
Checking Whether an Address Is in an Eligible Rural Area
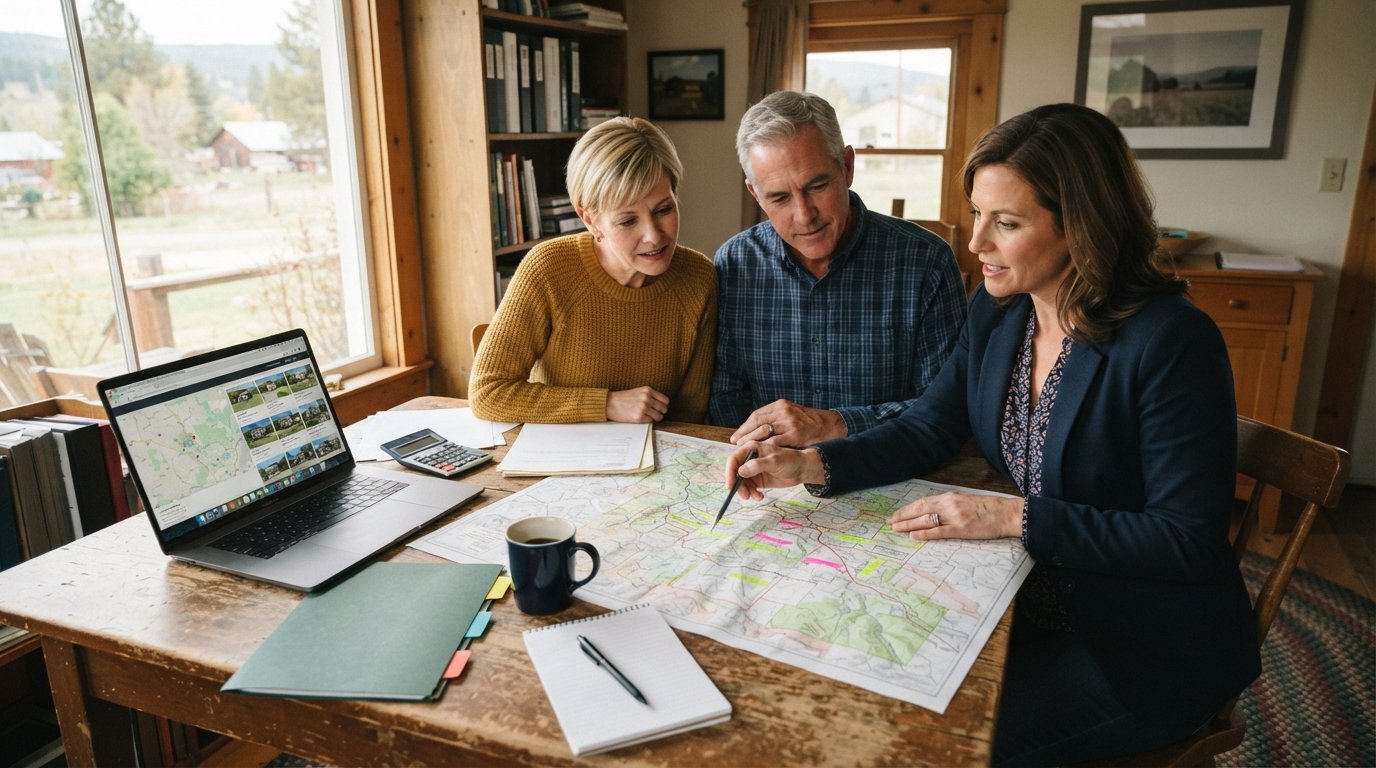
Location eligibility is the other half of the puzzle, and it is more nuanced than the word rural suggests. The USDA does not simply exclude big cities. It evaluates communities based on population and proximity to urban centers, and it maintains a map that shows eligible and ineligible parcels. Some towns with tens of thousands of residents qualify, while certain suburbs of major metros do not.
The fastest way to check is the USDA's online address lookup tool. You enter a specific property address, and the tool returns whether that location sits inside an eligible area. This matters because eligibility can change at the street level. A home on one side of a road may qualify while a development across the highway does not.
Several factors influence the boundaries:
- Population thresholds tied to the nearest urban area.
- Whether the community is economically tied to a larger metro.
- Updates to the rural area map, which can shift over time.
If you are shopping in a community near a growing city, check each address individually rather than assuming the whole town is eligible. Real estate listings rarely flag USDA eligibility, so this is one piece of homework you have to do yourself. The FHA, VA, and USDA loan programs explained for buyers offers a broader comparison if you are still deciding which program fits your situation.
Household Size and Its Effect on Limits
Household size does more than adjust the income ceiling. It also shapes how much house the program will help you finance, because the USDA considers the number of people who will occupy the home when reviewing the loan. A larger household may qualify for a higher income limit, but it also needs a home large enough to house everyone, which affects the purchase price and the monthly payment.
Consider an example. In a county where the four-person limit is $110,000 and the one-person limit is $75,000, a couple earning $90,000 with two children could qualify where a single applicant earning the same amount would not. The program is designed around the idea that more people in a home means more financial capacity and more need for space.
When you apply, be prepared to document everyone who will live in the home, including children and any relatives who share expenses. Lenders will ask for this information, and the USDA uses it to match your application to the correct limit. If your household size changes between application and closing, tell your loan officer, because the numbers may need to be recalculated.
What the USDA Program Does Not Do
MortgageDirectory is an educational resource, and it does not determine USDA eligibility, quote rates, or take applications. The same applies to any general guide: no article can tell you definitively whether you qualify. Only the USDA's official tools and a participating lender can make that call, and the final answer depends on your full financial picture, the specific property, and current program rules.
What this guide can do is help you ask better questions. Before you contact a lender, gather your household income documents, look up the address you are considering, and check the income limit for your county and household size. That preparation makes the conversation faster and helps you avoid falling in love with a home that was never eligible in the first place.
It also helps to understand the tradeoffs. USDA loans offer zero down payment and competitive rates, but they come with income caps, location rules, and fees that other programs may not have. Comparing them against conventional, FHA, and VA options gives you a clearer sense of which path suits your budget and timeline. For readers who want to explore mortgage products side by side, Express Mortgage Quotes provides a platform to compare quotes from verified lenders after you have done your educational groundwork.
Practical Steps Before You Apply
The application process goes more smoothly when you treat eligibility as a checklist rather than a guess. Start with the two big questions: does your household income fall under the limit for your county and household size, and is the property in an eligible rural area? If both answers are yes, you are ready to gather documents and talk with a USDA-approved lender.
Here is a sensible order of operations:
- Look up the income limit for your county and household size using the USDA's official tables.
- Add up gross income for every adult who will live in the home, including variable pay.
- Check the specific property address in the USDA eligibility map before making an offer.
- Gather pay stubs, tax returns, and employment documentation for all household members.
- Contact a participating lender to confirm your numbers and start the pre-qualification process.
Following this sequence prevents the most common disappointment: discovering after a contract is signed that the home sits just outside the eligible boundary or that a household member's income pushes the total over the cap. A few hours of research up front can save weeks later.
Common Misconceptions About USDA Eligibility
One persistent myth is that USDA loans are only for farms. In reality, the program serves rural communities of many kinds, including small towns, suburbs on the edge of metro areas, and even some larger communities that meet the population and economic criteria. You do not need to grow crops or own acreage to qualify.
Another misconception is that the income limit is the same everywhere. As covered above, limits vary by county and household size, and they update annually. Relying on a figure you heard from a friend in another state can lead you astray. Always check the current table for your specific location.
A third myth is that a pre-qualification letter guarantees eligibility. Lenders can pre-qualify you based on stated information, but the USDA's formal review comes later and can surface issues. Treat pre-qualification as a green light to keep exploring, not a final approval.
Where to Go for Authoritative Answers
The USDA maintains official resources, including income limit tables and the rural area map, that are updated regularly. These are the best sources for definitive answers about usda loan income limits and eligible rural areas. Local USDA offices can also answer questions about the direct loan program and specific property reviews.
For general mortgage education, including how loan terms, payments, and costs fit together, MortgageDirectory's guides and payment calculator can help you build a budget before you apply. The site does not quote rates or match lenders, but it does explain the mechanics in plain language so you can walk into a lender conversation prepared.
Rural homeownership is within reach for many buyers who assume they earn too much or live too close to a city. The key is checking the two variables that matter most, income and location, against the current rules for your specific situation. Do that homework first, and the rest of the process becomes far more predictable.