
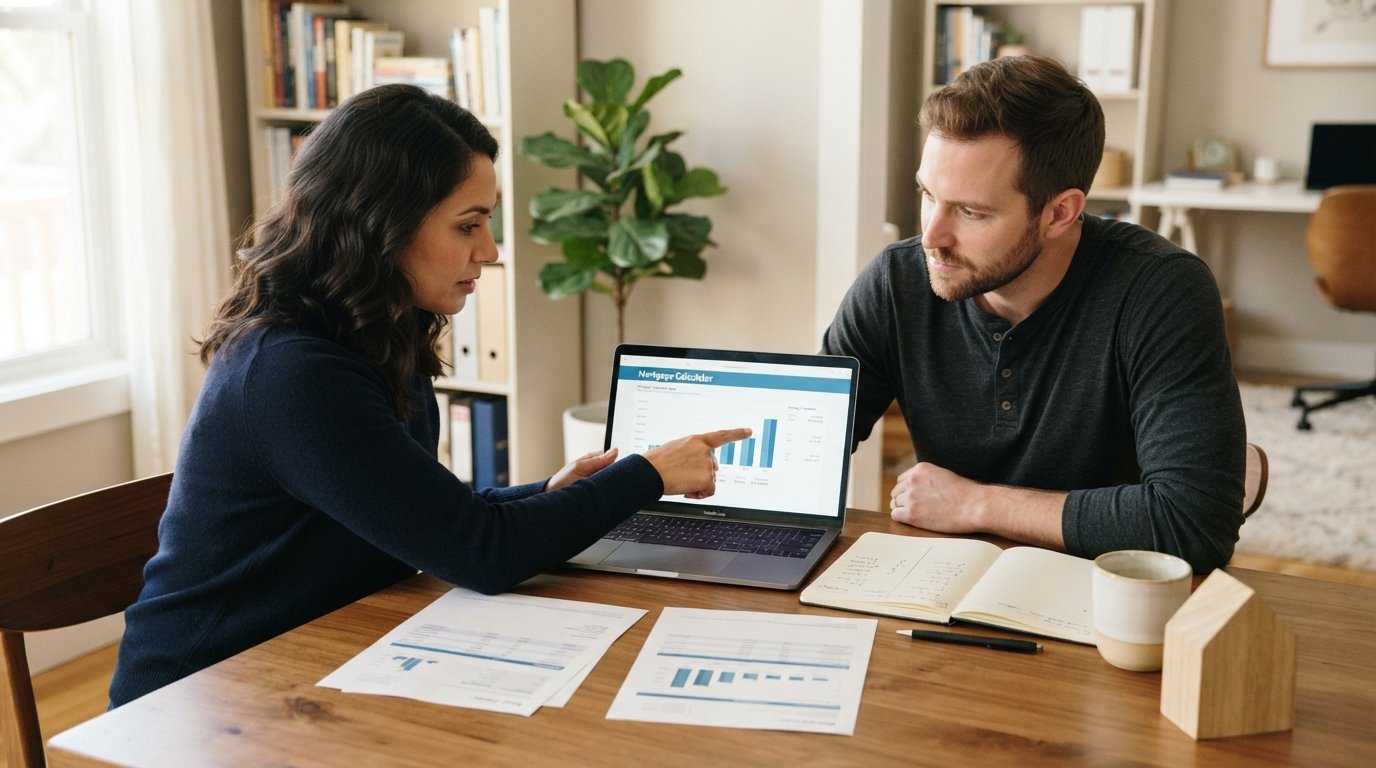
Using Mortgage Calculator to Compare Loan Scenarios
Using mortgage calculator to compare loan scenarios turns confusing offers into clear trade-offs, showing monthly payment and total interest differences.
By Samuel Keller
Two loan offers can look nearly identical on paper and still cost you tens of thousands of dollars more over time. The difference usually hides in the details: a slightly higher rate, a longer term, a smaller down payment that triggers private mortgage insurance, or an adjustable rate that resets after a few years. Comparing those offers side by side in your head is nearly impossible, which is why using a mortgage calculator to compare loan scenarios is one of the most practical habits you can build before you talk to a lender. A calculator turns each offer into the same language, dollars per month and dollars over the life of the loan, so you can see trade-offs clearly instead of guessing.
This guide walks through how to structure those comparisons. You will see which inputs matter most, how to model fixed versus adjustable rate loans, how down payment choices ripple through PMI and total cost, and how to read an amortization schedule without getting lost in the rows. Everything here is educational, not financial advice, and no calculator can predict your exact future. But a disciplined comparison process will help you ask better questions and recognize when an offer is genuinely better rather than just marketed better.
Start With the Inputs That Actually Move the Payment
Every mortgage calculator runs on the same core inputs: loan amount, interest rate, loan term, and the ongoing costs that get bundled into your monthly payment. The loan amount is not necessarily the purchase price; it is the purchase price minus your down payment. That distinction matters because two buyers looking at the same house can have very different loan amounts, and therefore very different payments, based on how much cash they put down.
The interest rate gets the most attention, and rightly so, but the loan term is equally powerful. A 30-year fixed loan spreads principal repayment over 360 payments, which keeps the monthly payment lower but increases total interest substantially compared with a 15-year loan. Property taxes, homeowners insurance, and HOA dues are often entered separately because they are not part of the loan itself, yet they affect your monthly outlay and your budget. If you are comparing two homes in different tax districts or with different HOA fees, those inputs can change the affordability picture more than a small rate difference.
Here is a simple checklist for gathering inputs before you sit down with a calculator. Having these numbers ready keeps the comparison honest and prevents you from mixing assumptions between scenarios.
- Purchase price and down payment amount (or down payment percentage)
- Interest rate for each offer, including whether it is fixed or adjustable
- Loan term in years (15, 20, 30, or another option)
- Estimated annual property taxes and homeowners insurance
- HOA dues, if any, and whether PMI applies
Once those inputs are in hand, the calculator produces a monthly payment broken into principal and interest, plus escrow items where applicable. That breakdown is the foundation for every comparison that follows. Without it, you are comparing marketing headlines; with it, you are comparing actual cash flow.
Comparing Fixed and Adjustable Rate Scenarios
Fixed-rate and adjustable-rate mortgages behave very differently over time, and a calculator helps you see where the paths diverge. A fixed-rate loan keeps the same interest rate for the entire term, so the principal and interest portion of your payment never changes. An adjustable-rate mortgage, or ARM, typically starts with a lower introductory rate for a set period, then adjusts periodically based on an index and margin. The initial payment on an ARM often looks more attractive, which is exactly why it deserves careful modeling rather than a quick glance.
To compare them fairly, run two scenarios with the same loan amount and term, using the fixed rate for one and the ARM's introductory rate for the other. Note the difference in monthly payment during the introductory period. Then ask what happens after the reset: if the rate rises by one or two percentage points, what does the payment become? Many calculators let you test a higher rate to see that adjusted payment. The gap between the introductory payment and the post-adjustment payment is your exposure, and it should be weighed against how long you plan to stay in the home.
If you expect to sell or refinance before the first adjustment, an ARM can be reasonable because you may never experience the reset. If you plan to stay long term, the fixed-rate loan provides certainty that an ARM cannot. The calculator will not make that decision for you, but it quantifies the trade-off so you can decide whether the lower initial payment is worth the future uncertainty. For readers who want a neutral reference point on how these products are structured, the plain-language guides at MortgageZone explain the mechanics without pushing a particular product.
Modeling Down Payments, PMI, and Total Cost
Down payment comparisons are where a calculator earns its keep. Changing the down payment changes the loan amount, the monthly principal and interest, and often whether private mortgage insurance applies. Conventional loans typically require PMI when the down payment is below 20 percent, and that insurance adds to the monthly payment without building equity. A calculator that includes a PMI field lets you see the real monthly cost of putting less down, not just the sticker price of the home.
Consider a hypothetical purchase where putting 10 percent down instead of 20 percent keeps more cash in reserve but adds a PMI premium each month. The calculator shows the higher monthly payment, and an amortization view shows how the smaller down payment affects the loan balance over time. You can then compare that monthly difference against the value of keeping cash available for emergencies, renovations, or closing costs. There is no universal right answer, but the comparison replaces guesswork with numbers.
Total interest is the other number worth tracking. A lower monthly payment achieved by stretching the term or choosing a smaller down payment often means more interest paid over the life of the loan. The calculator's total interest figure, sometimes shown alongside a payoff date, makes that trade-off visible. When you compare scenarios, look at both the monthly payment and the total interest, because a payment that fits your budget today can still be expensive over decades.
Reading the Amortization Schedule to See Where Money Goes
An amortization schedule lists each payment over the life of the loan and splits it into principal and interest. Early payments are weighted heavily toward interest, especially on long-term loans, because interest is calculated on the remaining balance. As the balance declines, more of each payment goes toward principal. Seeing this schedule for two competing scenarios reveals differences that monthly payment figures alone can hide.
For example, a 15-year loan has higher monthly payments but a much steeper principal curve, so you build equity faster and pay far less total interest. A 30-year loan with the same rate has lower payments but a slower equity build and more interest overall. If you are comparing a 30-year loan at a lower rate against a 15-year loan at a slightly higher rate, the amortization schedule shows which one accumulates equity faster in the early years and which one costs more in total. That context is useful whether your goal is lower monthly obligations or long-term savings.
The schedule also helps you evaluate extra payments. If you plan to pay a little extra toward principal each month, some calculators let you model that and see how it shortens the term and reduces total interest. Comparing a baseline scenario against an extra-payment scenario is a concrete way to decide whether accelerating payoff fits your budget.
A Step-by-Step Comparison Framework
With the inputs and concepts in place, the comparison itself becomes a repeatable process. The goal is to hold everything constant except the variable you are testing, so the differences you see are attributable to that variable. Mixing assumptions between scenarios, such as a different tax estimate for each offer, undermines the comparison.
- Enter a baseline scenario using your best estimates for price, down payment, rate, term, taxes, insurance, and HOA.
- Change one variable at a time, such as the interest rate or down payment, and record the monthly payment and total interest.
- Compare fixed versus adjustable structures using the same loan amount and term, and test a higher rate for the ARM reset.
- Review the amortization schedule for each finalist scenario to see equity build and total interest.
- Summarize the trade-offs in a simple table so you can discuss them with a lender or advisor.
This framework keeps the analysis disciplined. After a few rounds, patterns emerge: you may find that a small rate difference matters less than a PMI change, or that a shorter term is affordable only if the down payment stays at a certain level. Those insights are exactly what you want before entering negotiations, because they tell you which levers are worth pulling.
Common Pitfalls When Comparing Loan Scenarios
Even careful comparisons can go wrong if a few common mistakes slip in. One is ignoring escrow items: taxes, insurance, and HOA dues can vary widely between properties and can overwhelm a small rate difference. Another is comparing offers with different terms without normalizing the monthly payment and total interest. A 30-year loan will almost always have a lower monthly payment than a 15-year loan, but that does not make it cheaper overall.
A third pitfall is treating the calculator's output as a guarantee. Rates change, taxes are reassessed, insurance premiums shift, and ARM adjustments depend on future index values. The calculator is a planning tool, not a prediction. Use it to understand relative differences and to stress-test your budget, then confirm actual figures with lenders. Keeping a margin of safety in your budget is wise because the monthly payment you see today may not be the payment you face in a few years.
Finally, avoid comparing too many scenarios at once. A focused comparison of two or three finalists is clearer than a dozen variations, and it makes the trade-offs easier to explain to anyone helping you decide. The point of using a mortgage calculator to compare loan scenarios is clarity, not complexity.
Turning Calculator Results Into Better Conversations
The numbers from your comparison are most valuable when they shape the questions you ask. Instead of asking whether a rate is good in isolation, you can ask how a specific offer's total interest compares with another, or whether the lender's PMI estimate matches your model. You can ask about ARM caps and margins so you understand the worst-case adjustment. You can ask whether a slightly higher rate comes with lower closing costs, and model that trade-off.
Mortgage calculators are educational tools, and the results depend entirely on the inputs and assumptions you supply. Used consistently, they transform a confusing pile of offers into a structured comparison you can reason about. Start with clean inputs, change one variable at a time, read the amortization schedule, and keep a margin for the unknowns. That process will not tell you which loan to choose, but it will help you choose with your eyes open, which is the most any pre-lender research can do.